
Every Vagal vagus nerve stimulator is eligible for purchase with HSA (Health Savings Account) and FSA (Flexible Spending Account) funds. Because those are pre-tax dollars, using them effectively discounts a device by your marginal tax rate – for most people, a 20 to 30 percent saving compared to paying with taxed income. This guide covers what qualifies, the two ways to pay, and the deadlines worth knowing.
What qualifies
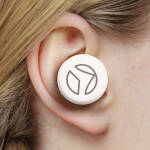
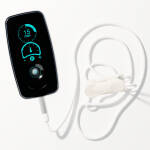
Our stimulators – the Vagal Buddy ($349), Vagal Oh! ($499) and tENS Vagal Boost ($59) – are HSA/FSA eligible, and accessories used with them, such as ear clips and conductive gel, generally qualify alongside the device. Eligibility rules are ultimately set by your plan administrator, so if you are unsure about a specific item, a quick check with them settles it.
Two ways to use your funds
1. Pay with your HSA/FSA debit card. If your plan issued you a card, use it at checkout exactly like any other card. This is the simplest route – no paperwork, the pre-tax saving is immediate.
2. Pay normally, then reimburse yourself. Pay with a regular card, keep your order confirmation, and submit it to your plan administrator for reimbursement. Your Vagal receipt shows the product name, date and amount – the details administrators ask for. If your plan needs a more detailed itemized receipt, contact us and we will provide one.
Do I need a Letter of Medical Necessity?
Many administrators approve eligible wellness devices without one, but some plans ask for a Letter of Medical Necessity (LMN) from a healthcare provider for certain purchases. If yours does, a short note from your doctor describing why vagus nerve stimulation supports your health is typically sufficient. Your administrator can tell you in one call whether an LMN applies to your plan.
Mind the FSA deadline
HSA money is yours indefinitely and rolls over year to year. FSA money is mostly use-it-or-lose-it: unspent balances are forfeited at the plan year’s end, with some plans offering a short grace period or a small carryover. If you have an FSA balance in November or December, a device you have been considering anyway is one of the more sensible ways to use it before it evaporates.
The math, briefly
Suppose you are in a combined 25 percent tax bracket. A $349 Vagal Buddy paid from taxed income requires about $465 of gross earnings. Paid from pre-tax HSA/FSA funds, it requires $349. Same device, roughly $116 kept – and the saving scales with your bracket.
Common questions
Does this work outside the US? HSA and FSA are US programs. Customers elsewhere may have analogous schemes (some Canadian HSAs, certain European health budgets) – check your local plan’s eligible-expense rules.
Is this the same as insurance coverage? No. Consumer wellness devices are generally not covered by health insurance; HSA/FSA is a way to spend your own pre-tax money on eligible health purchases. For the full pricing picture, see how much a vagus nerve stimulator costs.
Does the 45-day guarantee still apply? Yes – every device carries the 45-day money-back guarantee regardless of how you pay. If you return a device bought with HSA/FSA funds, ask your administrator how they handle refunded amounts.
Ready to use your funds? Browse stimulators, or take the 2-minute quiz to find the right fit. This article is general information, not tax advice – your plan administrator has the final word on eligibility for your specific plan.